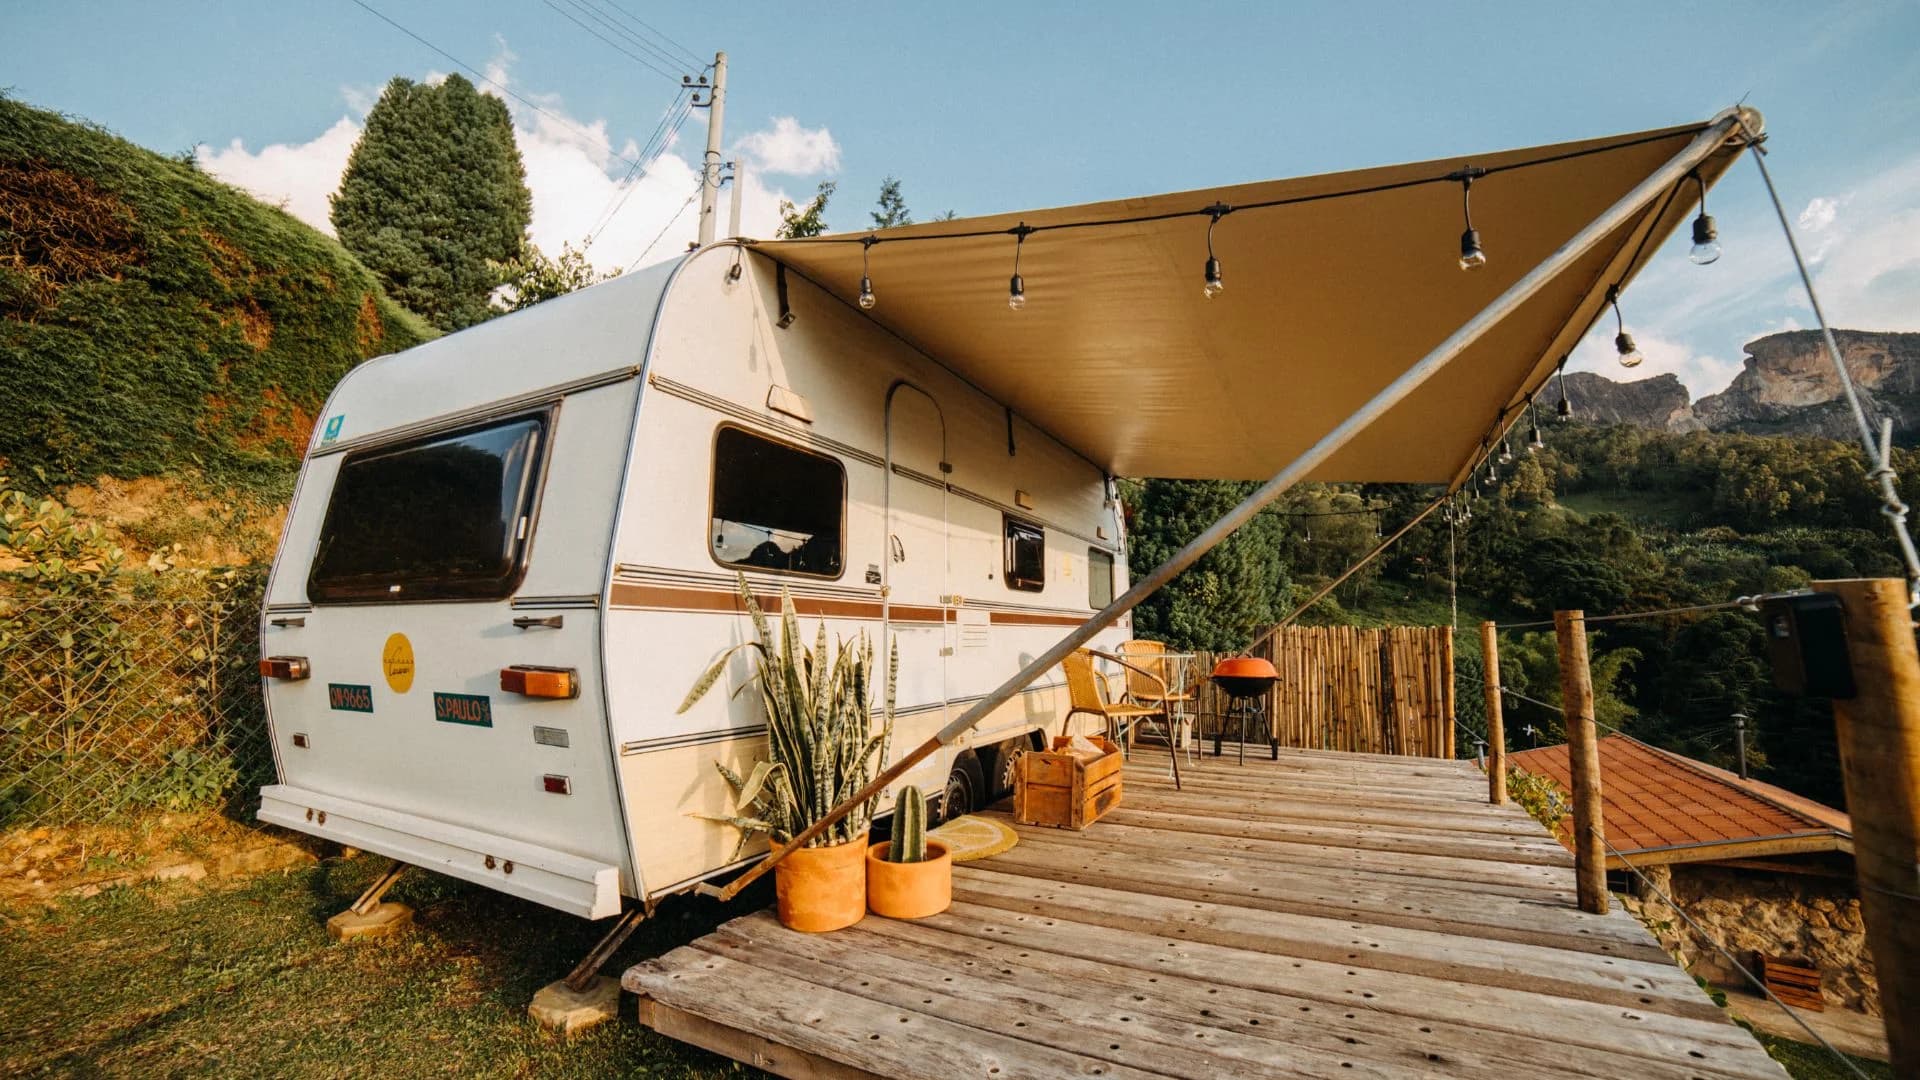
If you're working out how to finance a caravan or camper trailer in WA, there are two loan types, secured and unsecured, and three places to arrange finance: a lender, a broker or the dealership. What each one offers varies.
Which combination suits you depends on the van, your budget and how much of your savings you want to keep in reserve. WA adds one more thing to check, because caravans and camper trailers can be treated differently from cars when it comes to duty.
What types of loan can you use to buy a caravan?
There are two broad types: a secured loan and an unsecured personal loan. With a secured loan you offer an asset as security, and that's usually the caravan or camper trailer you're buying. With an unsecured loan, no asset is attached. Here's how that plays out.
Secured loan | Unsecured personal loan | |
What secures it | An asset, usually the caravan or camper trailer | No asset |
If you don't repay | The lender may be able to take possession of the asset and sell it to recover some of the debt | The debt remains enforceable; the lender needs a court order before it can take and sell assets |
Interest rate | Often lower than an unsecured loan | May be higher, because the lender carries more risk |
Getting the loan | Depends on the lender's criteria | Can be harder to get; depends on the lender's criteria |

Treat these as general tendencies. Lenders set their own criteria, so what you're offered depends on your circumstances and on the lender.
Can you use a personal loan for a caravan?
Yes. A personal loan for a caravan can be secured or unsecured, and the table shows what changes between the two. The name on the paperwork matters less than what's securing the loan. So ask the question directly: is this loan secured, and against what?
Should you finance a caravan or pay cash?
Paying cash means no interest and no repayments. Financing means you pay interest, and your savings stay available. Neither is the better choice in itself, and it's a decision only you can make.
These are the things to weigh up:
- how much you'd have left in savings after paying cash
- the other costs of travelling with the van, such as fuel, sites, servicing and unplanned repairs (our guide to what the Big Lap really costs sets these out)
- the total interest you'd pay over the life of a loan
- whether the repayments would sit comfortably in your budget.
What affects the interest rate and your repayments?
A few things shape the rate you're offered. One is whether the loan is secured: unsecured loans carry more risk for the lender, so they can be harder to get and may come with a higher interest rate. Another is the lender, because lenders use different criteria and you might qualify with one and not another. Your credit history plays a part too.
When you're weighing up offers, look for the comparison rate, which lenders are required to show when they advertise fixed-term consumer loans. It rolls the interest rate and most fees and charges into a single figure, which makes loans easier to line up on cost. It doesn't capture everything: government fees and charges are left out, and so are charges that only apply in certain circumstances, such as paying the loan off early. We cover this in more detail in our guide to comparing loan offers.
How do your deposit and loan term change the cost?
A bigger deposit means you borrow less, so there's less to pay interest on. The term works differently. For the same loan amount and interest rate, a longer term lowers each repayment and increases the total interest you pay. A shorter term does the reverse.
Neither is right or wrong. It comes down to what fits your budget each month against what you're happy to pay overall. You can test a few combinations in our loan calculator before you talk to anyone.
Do you pay stamp duty on a caravan in WA?
On a standard caravan or camper trailer, no. Stamp duty on vehicles is officially called vehicle licence duty in WA, and caravans that aren't motor propelled, and camper trailers, are exempt from it when they're permanently fitted for human habitation in the course of a journey. The Department of Transport applies the exemption automatically when the licence is granted or transferred. You'll still pay a transfer fee.
Two things sit outside that. The exemption is worded for vans that aren't motor propelled, so if you're looking at a motorhome or campervan, check the official duty calculator before you budget. The caravan exemption also does not extend to the tow vehicle; other exemptions may apply. As at October 2026, for vehicles of 4.5 tonnes or less, WA charges vehicle licence duty at 2.75% of the dutiable value up to $25,000, a sliding rate above $25,000 and up to $50,000, and 6.5% above $50,000.
Where can you arrange the finance?
The type of loan and where you get it are two separate decisions. You can go direct to a bank or lender, use a finance broker, or take up finance arranged through the dealership. The loan types available through lenders, brokers and dealers vary, so ask each one what it can arrange and don't assume the channel decides the loan type.
Dealer-arranged finance is convenient because it's sorted in the same place you buy the van, but it's still worth getting at least one other quote to compare it with. Comparing is what a broker does. Loans123 is a broker, not a lender, and we compare 30+ lenders. Here's how we're paid: we may receive commission from the lender and we may charge a fee, and both are set out in our Credit Guide.
What should you check before applying?
A lender wants to know the loan is affordable for you. In general terms, they look at:
- whether your income covers the repayments along with your regular expenses
- how secure your employment is
- your credit history.
It helps to go in with your own questions too. For any loan you're offered, ask:
- what the interest rate is, and whether it's fixed or variable
- how long the loan runs
- what happens if you miss a repayment
- what the total cost is once fees and charges are added.
Key Takeaways
- There are two loan types, secured and unsecured. Ask what's securing any loan you're offered.
- You can arrange finance through a lender, a broker or a dealership, and the loan types each one offers vary. Get more than one quote.
- Cash avoids interest and financing keeps savings available. Weigh up your remaining savings, your travel costs, the total interest and the repayments.
- For the same loan amount and interest rate, a longer term means lower repayments and more interest overall.
- In WA, non-motorised caravans and camper trailers fitted for habitation are exempt from vehicle licence duty. The caravan exemption does not extend to the tow vehicle; other exemptions may apply.
Thinking about financing a caravan or camper trailer? Call 1800 079 147, or visit our caravan finance page to start an enquiry and speak to a broker about your options.
This article provides general information only. It does not constitute financial advice. Please consider your personal circumstances before making any financial decisions. Loans123 holds Australian Credit Licence 512846.
Ready to see what you could borrow?
Loans123 compares more than 30 lenders from our Victoria Park office in Perth. Read more about our Caravan & RV Loans and Personal Loans, or get a quote now.
Checking your options has no impact on your credit score.
Written by
Trent Cray
Finance Specialist, Loans 123
Trent is a Finance Specialist at Loans 123 in Victoria Park, Perth. He helps customers compare more than 30 lenders to find car, personal and business finance that suits their situation.
Meet the Loans 123 team